Opportunity amid volatility
Emerging market debt is entering a more complex phase, but with income as the anchor and differentiation across countries and sectors back in play, active investors are finding renewed opportunity.

Emerging market debt has spent much of the past three years reaffirming its fundamental resilience. Now, as volatility returns to the global backdrop, the approach to the opportunity set must evolve beyond just surfing the beta of the market through yield or spread compression.
For Damien Buchet, chief investment officer at Principal Finisterre, the shift is less about direction and more about the right mix of performance drivers.
‘This is no longer a simple beta trade,’ he said. ‘The opportunity today is a combination of maximizing a diversified income stream and the ability to capture idiosyncratic alpha.’
Having endured what Buchet describes as a ‘perfect storm’ in 2022 and 2023 – from aggressive global monetary tightening to commodity shocks and refinancing pressures – many emerging economies have come out stronger from the recent cycle, with improved fundamentals and policy credibility.
‘In many ways, emerging markets went through their reckoning earlier,’ he said. ‘What developed markets are grappling with today – fiscal credibility, policy discipline, commodity shocks – many emerging countries have already adjusted to.’
That is reflected in improving fundamentals. Rating upgrades have outpaced downgrades since 2023 (and still do, for example the recent upgrades of Argentina and Nigeria), while growth has remained relatively stable. Even as global activity moderates, emerging markets ex-China are still expected to expand at more than 3% in 2026.
Before the latest bout of geopolitical disruption, Buchet describes the backdrop as broadly ‘Goldilocks’: steady growth, contained inflation, stronger policy credibility and positive ‘terms of trade‘.
‘Investors are reassessing developed markets and rediscovering the diversification and extra income that emerging markets can offer’
‘Since late 2023, growth has been holding up, inflation stayed under control, and policy credibility improved,’ he says. ‘That created a very supportive environment for emerging market debt, which remained otherwise extremely under-owned by global investors.’
Real yields across many emerging markets remain elevated by historical standards, while inflation has been broadly contained outside a handful of idiosyncratic cases. At the same time, a more stable dollar backdrop has eased one key external pressures that typically weighs on the asset class.
Commodity dynamics have also been constructive. Until recently, energy markets have been more balanced than in previous cycles, while industrial metals and key export prices have supported terms of trade for many economies, reinforcing external stability.
After heavy outflows in 2022 and 2023, capital has started to return to emerging market debt, drawn by its income profile and diversification benefits at a time when confidence in developed markets has been tested.
‘The strategic commitment from larger allocators we saw in late 2025 and into early 2026 has held,’ Buchet said. ‘Investors are reassessing developed markets and rediscovering the diversification and extra income that emerging markets can offer. The recent geopolitical developments have not changed that for now.’
Importantly, the nature of those inflows has been gradual rather than speculative, reflecting a reassessment of long-term allocation rather than a tactical rebound. That distinction, Buchet says, is key to the durability of the move.
A more divided opportunity set
If the backdrop had been broadly supportive, recent events have made it more complex. Geopolitical tensions in the Middle East and the resulting disruption to energy markets have introduced a new layer of uncertainty. Rather than undermining the investment case, Buchet argues it has sharpened it.
‘The outcome of the Iran war has been to reintroduce discrepancies between potential winners and losers across markets,’ he said. ‘The right portfolio manager, with the right level of flexibility, can differentiate between those alpha opportunities.
‘If you’re constrained by an index, your ability to exploit those discrepancies is limited. In emerging markets, those divergences between countries, sectors, and currencies are exactly where value is created.’
Dispersion now runs across multiple dimensions of the asset class. Energy exporters and commodity-linked economies have benefited from recent price moves, while more fragile, import-dependent countries are facing renewed pressure on external balances.
Within regions, policy credibility is also increasingly divergent, with reform-oriented economies trading differently from those where fiscal or monetary discipline is weaker. This, he argues, makes the current environment fertile for active investors, with risks across the various EMs being visible enough and well identified by investors. ‘As always, crises only occur when people are long risk, wrongfooted and surprised. I don't see that today across EM debt,‘ Buchet said.
‘It’s about picking your battles and focusing on the fundamental winners or idiosyncratic improvers’
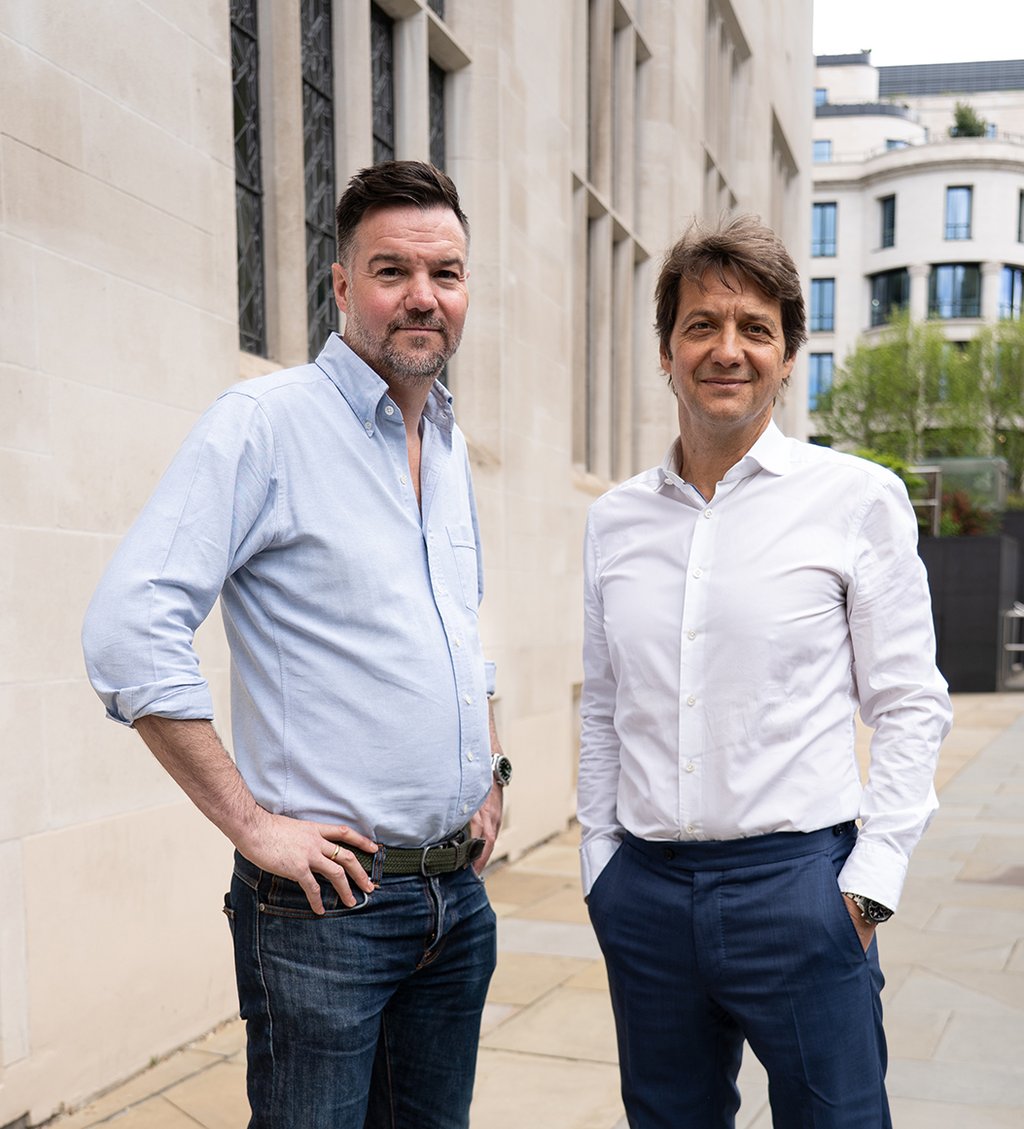
Across the opportunity set, Buchet and senior portfolio manager Christopher Watson, both Citywire AA rated, see the strongest value emerging outside mainstream sovereign credits.
‘The biggest value today is in local rates,’ Watson said. ‘Markets are overpricing the risk of a return to hiking cycles.’
Recent repricing across several markets has created entry points, particularly where central banks retain credibility and inflation remains contained. Latin America continues to feature prominently, supported by favourable terms of trade, while parts of Eastern Europe and select frontier markets offer improving fundamentals.
In currencies, the focus is on higher yielding markets in Africa, Turkey or Latin America where income compensates for volatility. In credit, the approach is more selective.
‘In aggregate, there’s less value in sovereign credit,’ Watson added. ‘It’s about picking your battles and focusing on the fundamental winners or idiosyncratic improvers.’ The corporate debt sector continues to offer fundamental visibility in many sectors amidst a more stable currency landscape, which still makes a short to mid duration positioning an attractive and diversifying income proposition.
Income, diversification, and flexibility
Across Principal Finisterre’s emerging market debt strategies, the current thread is a focus on income as the primary driver of returns, with a range of income-focused portfolios constructed to maximise the contribution from carry rather than capital appreciation.
‘If most of your return comes from the coupon stream, you have much greater visibility on outcomes,’ Buchet said. ‘That’s the anchor for everything we do.’
The two main Finisterre income strategies – the EMD Euro Income strategy, especially designed for Eurozone investors, and the USD-based EMD High Income strategy for other regions – differ in risk and currency exposure but share a common framework. The EMD Euro Income strategy is positioned more conservatively, with active currency management and a higher quality credit profile aimed at reducing volatility for euro-based investors. The other takes on more credit risk and greater exposure to US dollar assets in pursuit of higher yield.
Despite these differences, both are built around the same core philosophy: a short-duration bias, broad diversification and a strong focus on the maximization of the income stream as a key driver of portfolio returns, at the expense of price volatility.
In an income strategy, the expression of strong bottom-up fundamental convictions is central to the approach. Rather than reacting mechanically to market moves, the team reassesses each position based on whether the risk for each underlying issuer has fundamentally changed.
‘This is about being paid appropriately for the risk you take,’ Buchet said. ‘The key question is always whether the fundamental risk for your issuer has actually increased as a result of a short term market selloff. If it hasn’t, then periods of volatility can create opportunities rather than reasons to sell.’
For Buchet, the EM debt market cycle has entered a more mature phase. The broad, beta-driven recovery that followed the turbulence of 2022 and 2023 is giving way to a more selective environment, where returns are increasingly driven by income and active macro and credit-picking considerations.
In a world where traditional assumptions about the safety of developed markets are increasingly being questioned, that income-led case is becoming harder for investors to ignore.
‘Emerging market fixed income is where one can still see value for money – how much you’re being paid for the risk you take,’ Buchet said. ‘We believe this combination of reward versus risk remains most optimal in emerging markets.’


Fund facts
Finisterre Emerging Markets Debt High Income Fund
FUND SIZE:
$102.18m*
BASE CURRENCY:
USD
LAUNCH DATE
30 March 2026
SFDR CLASSIFICATION:
Article 8
INVESTMENT PHILOSOPHY:
An income-anchored solution within EMD, aiming to enhance yield and minimize risk.
ISIN / BLOOMBERG TICKERS:
Institutional share class (I Acc): IE000JPWS963/ PFEMDIU
Finisterre Emerging Markets Debt Euro Income Fund
FUND SIZE:
€248.28m*
BASE CURRENCY:
Euro
LAUNCH DATE
28 August 2020
SFDR CLASSIFICATION:
Article 8
INVESTMENT PHILOSOPHY:
An active EMD income strategy, long-biased investing. Carry-driven in EUR.
ISIN / BLOOMBERG TICKERS:
Institutional share class (I Acc): IE00BJK0G937/PRDEIIE
Retail share class (A Acc): IE00BJK0G374 / PRDEIAE
*As at 30 April 2026.
